AI Budgeting System: Organize Money in 45 Minutes
Organizing Your Finances with Artificial Intelligence: A Practical System for Smarter Budgeting
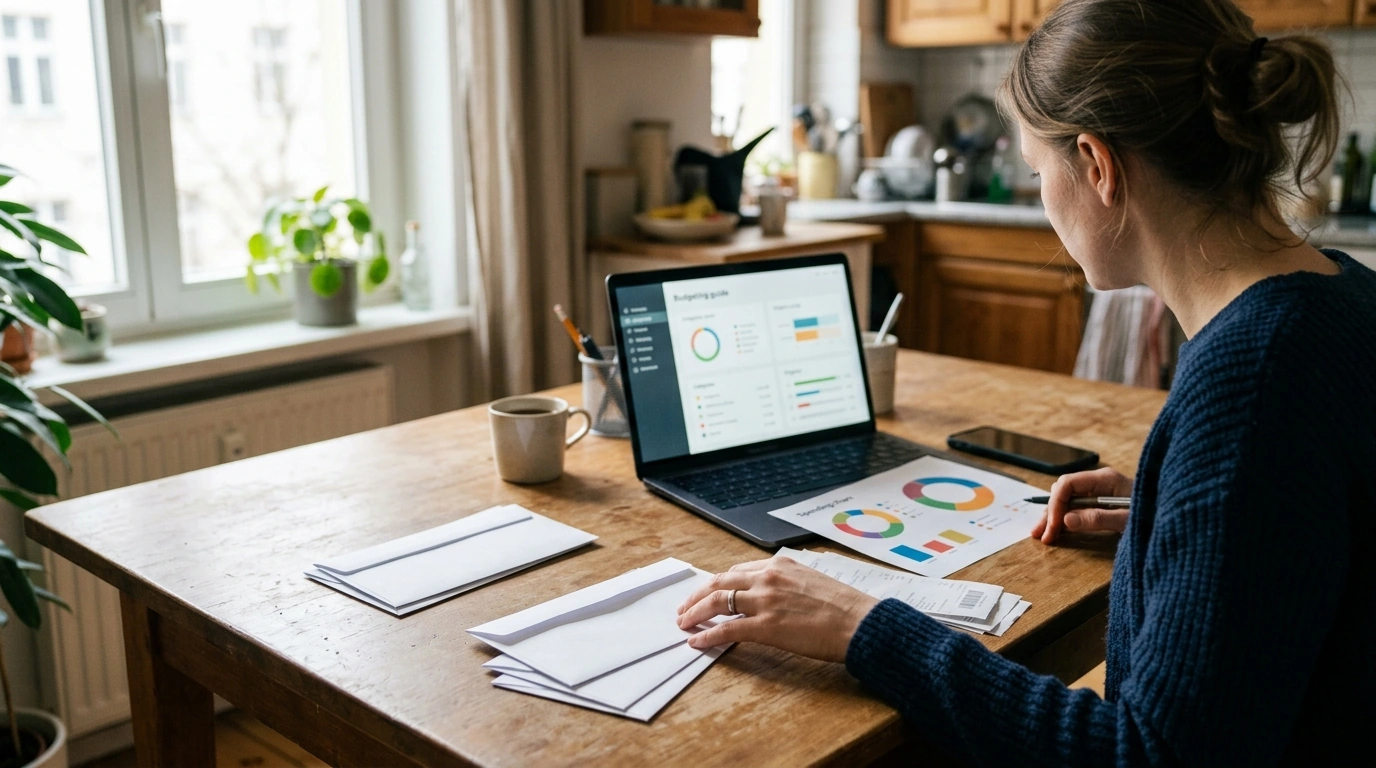
Money organization often breaks down for predictable reasons: inconsistent tracking, vague categories, forgotten bills, and budgets that don’t adjust when life changes. Artificial intelligence can reduce the busywork by spotting patterns, forecasting cash flow, and turning messy spending history into clearer next steps. The goal isn’t to hand your finances over to a bot—it’s to use AI as a fast analyst so your monthly budgeting, bill planning, and goal tracking become easier to maintain.
What AI Can (and Can’t) Do for Personal Finance
Used responsibly, AI can speed up the most annoying parts of money management—especially the “where did my money go?” phase.
- Translate transaction history into categories, trends, and summaries much faster than manual spreadsheets.
- Surface patterns that are easy to miss, like subscription creep, seasonal spikes, and “small” daily purchases that add up.
- Suggest budget targets and adjustments based on real spending behavior instead of guesswork.
- Forecast near-term cash flow to help prevent overdrafts and missed bills.
- Important limitations: AI can be wrong, may miscategorize, and can’t replace professional tax or legal advice.
For practical budgeting fundamentals and cash-flow concepts, the Consumer Financial Protection Bureau (CFPB) is a solid reference point. For safe use of AI and avoiding misleading claims, the Federal Trade Commission (FTC) provides useful guidance.
Set Up Your AI-Assisted Money System in 45 Minutes
This setup is designed to be simple enough to repeat. Complexity is usually what kills consistency.
Step 1: Gather the basics
Pull the last 2–3 months of transactions, current balances, a list of monthly bills, and your income dates. A 90-day window is usually enough for patterns without being overwhelming.
Step 2: Choose a single “source of truth”
Pick one place where your numbers live: a budget app, a spreadsheet, or a folder of bank exports. Multiple systems create duplicate totals and confusion.
Step 3: Use a simple category structure
- Needs (housing, utilities, groceries, transportation)
- Financial Goals (debt payoff, emergency fund, retirement)
- Lifestyle (dining, entertainment, shopping)
- Irregular/Annual (car repairs, gifts, annual subscriptions)
- Buffer (small surprises and timing mismatches)
Step 4: Define bill rules
Decide what must be paid first, what can be scheduled, and what can potentially be renegotiated (rates, plans, or due dates). If paycheck timing is an issue, consider reviewing withholding and pay planning with the IRS Tax Withholding Estimator.
Step 5: Use AI for an instant spending summary
Ask AI to summarize spending by category and list the top five drivers of outflow. Then sanity-check anything that looks off (common mislabels: big-box stores, delivery services, and payment processors).
Quick start checklist
| Task | What to collect | Output to produce |
|---|---|---|
| Transaction review | 90 days of transactions | Top categories + recurring charges list |
| Bills calendar | Due dates + minimum payments | Monthly bill schedule |
| Income map | Pay dates + typical amounts | Paycheck-to-bill alignment |
| Goal targets | Savings/debt goals | Monthly contribution plan |
| Buffer plan | Typical month variability | Minimum cash cushion amount |
Smart Budgeting: Let AI Build a Budget You’ll Actually Follow
The fastest way to quit budgeting is to start with “aspirational” numbers that don’t match reality. AI is most helpful when it turns your recent spending into a baseline.
- Start with reality-based baselines: use AI-generated averages from recent spending as your first draft.
- Set guardrails instead of strict limits for flexible categories like groceries, dining, and fuel (example: a target range).
- Let AI propose caps, then edit manually based on your values and priorities.
- Create if-then rules: if dining is over target mid-month, then pause nonessential shopping until next payday.
- Check weekly for 10 minutes: small course corrections beat end-of-month regret.
A practical approach is to keep “Needs” steady, protect “Financial Goals” with scheduled transfers, and adjust “Lifestyle” first when you need to recover from overspending.
AI for Cash-Flow Planning: Prevent Surprises Before They Happen
Budgeting is about totals; cash flow is about timing. Timing is where missed payments and overdrafts usually happen.
- Build a simple timeline: income dates on top, bills and recurring charges underneath.
- Ask AI to identify collision points where multiple bills hit before the next paycheck.
- Prioritize stability: rent/mortgage, utilities, insurance, minimum debt payments, then goals, then discretionary spending.
- Use sinking funds for irregular expenses (car repairs, gifts, annual renewals) to smooth out spikes.
- Maintain a buffer category so small deviations don’t break the entire month.
Once collision points are visible, the fix is often simple: change due dates where possible, split payments, or hold a slightly larger buffer until your cycle stabilizes.
Automate the Right Things (Without Losing Control)
Privacy and Safety When Using AI with Financial Data
A Simple 30-Day Routine to Stay Organized
Using a Guided Framework for Faster Results
For a structured walkthrough focused on AI-assisted budgeting and money organization, see Organizing Your Finances with Artificial Intelligence (eBook).
- Content That Sells Strategy Toolkit | How to Create a Content Marketing Strategy 3-in-1 Bundle
- Grow Your Business Step-by-Step: 10-in-1 Bundle for Online Success
FAQ
Is it safe to use AI tools for budgeting?
It can be safe when you minimize shared data, redact identifiers, choose reputable tools with clear policies, and verify AI outputs against your bank records. Use exports or read-only data whenever possible and avoid sharing anything that could enable account access.
What should be automated first when trying to get organized?
Start with fixed bills, minimum debt payments, and scheduled savings transfers so the essentials happen even on busy weeks. Keep a weekly review and alerts so automation doesn’t hide problems.
How quickly can AI help improve a budget?
Transaction summaries can provide immediate insights, and many people see measurable improvements within 2–4 weeks with weekly check-ins. Stronger results typically show up over 2–3 months as patterns stabilize and categories get refined.




Leave a comment